
Thank you for Subscribing to Real Estate Business Review Weekly Brief

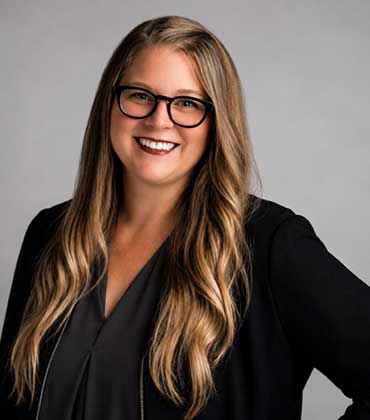 Michelle Steinmetzer, President
Convenience and transparency have become defining expectations across the real estate transaction, driving the adoption of digital processes at nearly every stage. Yet earnest money, one of the most critical steps, has remained dependent on paper checks and wires, manual verification and fragmented communication. Limited visibility leaves stakeholders uncertain about where funds stand, while manual verification processes add security risks and administrative burden.
TrustFunds is changing that by bringing earnest money into the digital transaction workflow while building trust and visibility into every step of the process.
The first company in the U.S. to facilitate digital earnest money, TrustFunds connects buyers, agents, brokers and designated earnest money holders through the same workflow. It modernizes trust in real estate by turning earnest money into a transparent and connected workflow within the multiple listing service (MLS) ecosystem.
“We’re not simply digitizing a payment; we’re creating confidence among all parties involved in the transaction,” says Michelle Steinmetzer, President.
TrustFunds platform connects the MLS, buyers, agents, brokers and designated earnest money holders within a shared workflow, giving every authorized participant visibility into the same transaction. By removing administrative friction from the transaction, TrustFunds enables professionals to spend less time managing payment logistics and more time serving their clients.
Making Every Payment Step Visible
TrustFunds gives participants visibility into where funds stand without requiring repeated status checks. Agents can initiate earnest money requests directly from their existing MLS workflow, allowing them to incorporate digital earnest money into established processes. Electronic submission allows buyers to send earnest money at any time, eliminating delays caused by travel, scheduling conflicts, office hours or physical delivery. Once the payment is submitted, automated status notifications keep relevant parties informed through processing and final deposit.
TrustFunds was designed with security as a foundational principle. Buyers enter banking information directly, eliminating the need to share sensitive financial details through emails, text messages or paper forms. Instead of relying on manual follow-ups to track whether funds have been submitted, received or deposited, participants share a real-time view of each transaction. That lets them focus on resolving issues rather than locating information.
Every step of the transaction is electronically tracked, time-stamped and documented, creating a complete audit trail from payment initiation through final deposit.
The platform also incorporates agent verification, monitoring controls and reporting capabilities that support fraud prevention and regulatory compliance. Documentation retention, user permissions and account-holder controls provide the accountability needed to accommodate varying trust-account and regulatory requirements across markets.
-
We’re Not Simply Digitizing A Payment; We’re Creating Confidence Among All Parties Involved in the Transaction.
In 2026, it completed its SOC 2 Type I audit and is currently in the process of securing the SOC 2 Type II compliance. The audit reinforces its commitment to maintaining strong controls around security, availability and data protection.
Driving Adoption through Existing Industry Relationships
In a highly relationship-driven industry like real estate, agent advocacy is an important driver of growth. When agents have a positive experience, they share it with colleagues, brokerages and teams.
TrustFunds builds adoption through relationships within the real estate industry. Its Business Development team establishes the connections that bring the platform into new markets, and designated earnest money holders, while it’s Implementation and Support team to activate and engage users.
“Once professionals see the transparency, security and efficiency, the conversation shifts from ‘Why would I change?’ to ‘Why weren’t we doing this sooner?’” says Steinmetzer.
As the industry continues to evolve, TrustFunds is focused on developing solutions that simplify transaction workflows, enhance security, and deliver greater value to real estate professionals and their clients.
By bringing earnest money out of the black box and into a transparent digital workflow, TrustFunds is creating a more transparent, secure and connected transaction experience for buyers, agents, brokers and other earnest money holders.
Earnest Money Payments without the Blind Spots
Earnest money still exposes a surprisingly manual fault line in otherwise digital real estate transactions. Contracts may be signed online, and activity tracked inside transaction systems, yet payment delivery can still depend on paper checks or wires, office hours and personal follow-up. That gap creates more than inconvenience. A delayed deposit can affect contract deadlines, while copied checks, emailed images and unattended paperwork expose sensitive bank information.
Payment status is often the first buying test. Agents need to know whether a buyer has submitted funds, while brokers or escrow holders need confirmation that processing has begun and the deposit has cleared. A system that merely accepts an electronic payment but leaves status buried in a separate portal does little to reduce follow-up. Useful platforms provide timely updates, supported by accessible records and automated notifications.
Security requires equal scrutiny because earnest money sits inside a fraud-prone stage of the transaction. Buyers should enter banking details directly into a protected payment environment rather than sending information through paper forms, or other electronic sources such as email. Electronic time stamps and retained transaction records help establish who initiated a request and how the payment progressed.
Workflow fit determines whether those controls are used consistently. Agents are unlikely to adopt a separate application that demands another login, account setup or repeated data entry during an active deal. Integration with the multiple listing services (MLS) reduces that friction. The payment request should begin where the agent already works and connect the buyer to the approved earnest money holder without forcing staff to relay confirmations manually.
Accountability extends beyond the front-end experience. Brokerages, title agencies and law firms may follow different trust account procedures or documentation rules. Decision-makers should examine permissions and reporting depth alongside record retention and onboarding requirements for each holder. The platform must support local process differences without allowing each office to create an uncontrolled workaround.
Availability matters as well. A buyer may receive an accepted offer after business hours or while traveling, and the contractual clock does not pause until a branch opens. A secure payment link that remains available around the clock removes the physical handoff while giving relevant parties early notice that funds are in motion.
“Trustfunds Gives Authorized Parties Status Visibility and A Documented Payment History From Initiation Through Final Deposit.”
TrustFunds emerges as a leading option with its MLS-integrated process designed specifically for earnest money. Agents can initiate requests from an MLS property listing without requiring buyers to create an account or download an app. It gives authorized parties status visibility and a documented payment history from initiation through final deposit.
Electronic tracking and user permissions are reinforced by reporting and retained documentation that support regulated trust account processes. For real estate organizations aiming to remove paper and wire handling without creating a disconnected payment channel, TrustFunds merits close consideration.
...Read more
Earnest Money Payment Processing Solutions Info
Q1
What Do Earnest Money Payment Process Solutions Handle?
Earnest Money Payment Process Solutions move the deposit stage of a real estate transaction into a digital workflow. They can support electronic earnest money collection, payment tracking and status communication without relying entirely on paper checks, wire transfers or manual handoffs. The practical benefit is straightforward: fewer disconnected steps and a clearer record of where a deposit stands. Good platforms should also fit the transaction process already in place, so users are not forced to duplicate work simply to send or monitor a payment.
Q2
How Does TrustFunds Simplify Earnest Money Payments?
TrustFunds applies Earnest Money Payment Process Solutions through a platform built into multiple listing service workflows. Users can enter the service without separate credentials, passwords or applications, while transaction details can be auto-populated from MLS data. Real-time status updates give involved parties a clearer view of payment progress. The result is a more direct path from transaction information to electronic earnest money processing, with fewer points where users have to re-enter data or move between disconnected systems.
Q3
Why Does Security Matter in Digital Earnest Money Processing?
Financial information sits at the center of the deposit process, so security is a basic requirement for Earnest Money Payment Process Solutions. Digital processing can reduce reliance on physical checks and limit situations where bank information is copied, carried, emailed or stored in less controlled ways. Buyers and organizations should look for protected data handling, controlled access and clear transaction records. Convenience matters, but it should never come at the expense of how sensitive payment information is handled.
Q4
How Do Earnest Money Payment Process Solutions Improve Transaction Visibility?
Earnest Money Payment Process Solutions can replace scattered status checks with a more consistent digital record of payment activity. Real-time status updates help authorized stakeholders see whether an earnest money step has been started, is moving forward or has been completed. Reporting tools can also support reconciliation and recordkeeping. That visibility matters because uncertainty around a deposit can create extra calls, follow-ups and handoffs at a point when transaction participants need a dependable view of progress.
Q5
What Practical Workflow Features Does TrustFunds Provide?
TrustFunds supports Earnest Money Payment Process Solutions with functions tied to MLS-connected real estate transactions. Its platform can auto-populate transaction details, give teams access to transaction information and send payment-status notifications. It also supports reporting and file exports for organizations handling reconciliation. Buyers retain control of their bank account information rather than passing those details through multiple hands. These features connect payment initiation, communication and back-office recordkeeping within the same electronic earnest money workflow.
Q6
What Should Organizations Evaluate in an Earnest Money Payment Platform?
A useful review of Earnest Money Payment Process Solutions should go beyond whether a platform can accept an electronic payment. Organizations should consider how well it fits existing workflows, how much information users must enter manually, how payment status is communicated, how users and earnest money holders are vetted, and how sensitive financial data is protected. Reporting and reconciliation support also affect day-to-day use. The better fit is usually a platform that removes unnecessary steps while keeping the earnest money process accurate, traceable, and secure for authorized participants.
